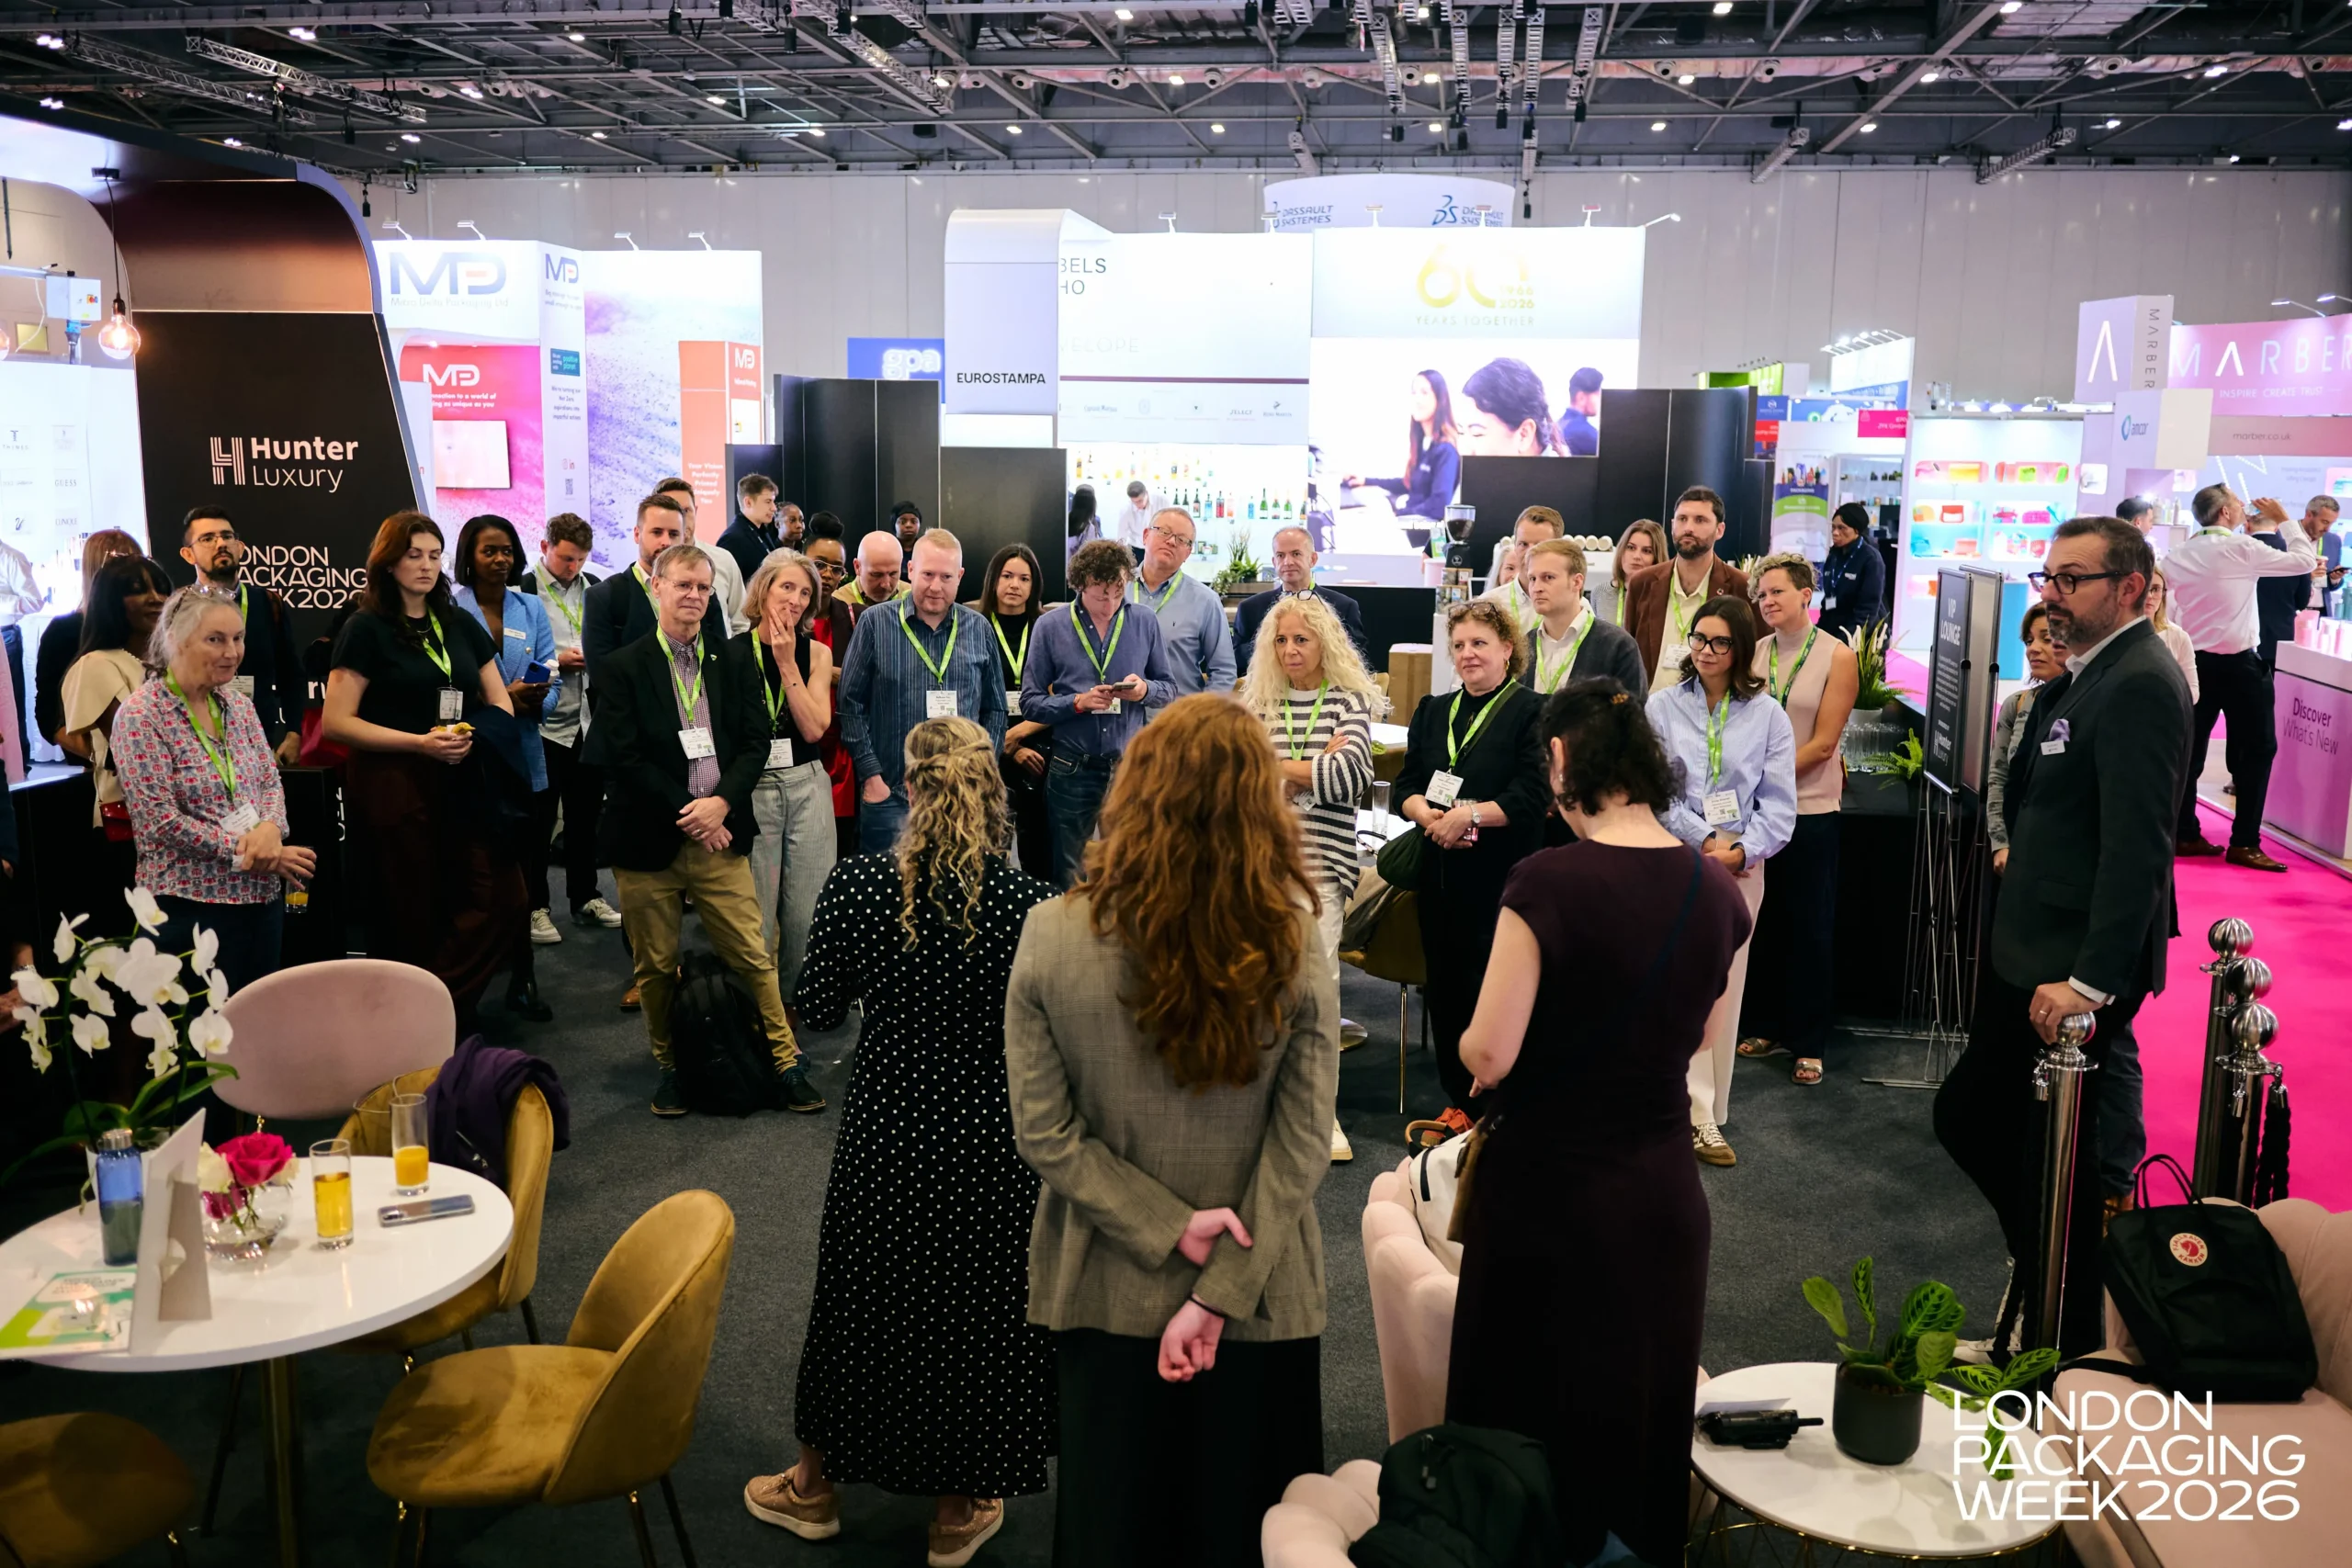
I spent last week at London Packaging Week, which landed square in the middle of Recycle Week 2026, just as PackUK wrapped up Year One of pEPR. Three ideas kept surfacing wherever I went: on the regulatory stage, in a circularity panel featuring brands from very different categories, and in the honest, off-the-cuff conversations between attendees. First, packaging regulation is compounding fast enough that it has become a genuine board-level issue. Second, regulation is a clear priority for every company right now, but balancing design changes against consumer needs and expectations is a genuinely tough balance to strike, and getting it right matters. And lastly, the industry is turning to collaboration, in councils, associations, working groups and events like this one, to keep pace and help shape what comes next.
1. The only constant is change, and it’s now a boardroom problem
PackUK used the show to share the results of the end of Year One of packaging EPR, and the headline figures tell their own story: roughly £1.4 billion collected from around 4,300 producers, distributed to 388 local authorities, run by a headcount of just 65 people across all four nations.
The more revealing number sat inside the first year of Recyclability Assessment Methodology data. Roughly one in seven producers are currently placing packaging that rates all red, meaning it doesn’t fit cleanly into today’s recycling systems, and only around one in ten producers are submitting fully green portfolios, with everyone else falling somewhere in between. The fee penalty on red packaging starts at 20% this year and is scheduled to reach 100% within three years, which turns a packaging decision made two years ago into a line a finance director now has to explain.
That’s why the fee conversation has genuinely moved into the boardroom. Estimated or reconstructed data doesn’t hold up well against a board watching fees climb year over year, and more than one conversation on the show floor suggested that UK producer fees already feel higher than comparable schemes elsewhere in Europe. That’s worth treating as sentiment rather than a settled comparison, since fee structures vary so much market to market, but it’s sharpening the scrutiny either way. Part of that scrutiny traces back further upstream: with so many regulations moving at once, and packaging teams now working alongside regulatory and procurement colleagues day to day, keeping supplier and collection data properly refreshed has become its own recurring challenge, and it’s hard to defend a fee number in the boardroom if the data behind it hasn’t kept pace. Nobody has a settled answer yet for how EPR fees will sit alongside deposit return scheme fees once UK DRS arrives in 2027, and that’s exactly the kind of open question worth modelling for rather than waiting on.
DRS is also a useful reminder that none of this is a uniquely British phenomenon. The UK’s own version launches in October 2027 chasing an ambitious return rate, a target that looks achievable given what similar schemes have already delivered elsewhere. Switzerland introduced its own packaging ordinance this year, built on the same underlying logic as the EU’s PPWR even though it sits outside the EU. The specifics vary market to market. The direction doesn’t. Layer that on top of Ireland, where teams already juggling both PPWR and UK pEPR across the island are finding the overlap between the two genuinely hard to untangle, and it’s clear why more than one person on the show floor reached for the phrase “once in a generation” to describe the pace of change packaging is absorbing right now.
Digital Product Passports are the next chapter nobody has fully written yet. The smart move is getting ahead of that conversation now, and framing plans in five-year terms out to 2030 or 2031 rather than deadline by deadline, a discipline several speakers were already modelling on stage.
The pattern worth building toward is the same regardless of which regulation is topical this quarter. Collect the data once from suppliers, in a way that’s genuinely frictionless for them to share rather than another form to fill in. Capture it in one connected model that serves EPR, RAM, PPWR, DRS, DPP and whatever comes next, rather than a fresh spreadsheet for each new acronym. Catch the inconsistencies before they ever reach a report or a board pack. Comply on demand, however the next requirement is worded. A fee, an assessment or a declaration is only ever as defensible as the specification data sitting behind it, and that foundation only holds if suppliers are treated as partners in providing it rather than another compliance box to chase.
2. Regulation and Consumer Demand Are Reshaping Sustainable Packaging Together
The same tension showed up again in a circularity panel featuring Danone, CTPA, the Scotch Whisky Association and Belu Water, and again in a candid conversation recorded for the show’s podcast with PZ Cussons’ packaging lead. The thread running through both: how do you hit a recyclability target, or a broader sustainability compliance goal, without losing what makes someone want to buy the product in the first place? Danone spoke to the operational reality of testing deposit return in a live market at Wimbledon and closing the gap between a scheme existing and shoppers actually understanding it. CTPA highlighted that recycled content in cosmetics has to clear a high safety bar, which is pushing that sector to also look at refill and reuse rather than material substitution alone. The Scotch Whisky Association’s contribution read as more cultural than technical: how to modernise packaging for a new generation of drinkers without alienating decades-long loyal customers, and how much of that pressure is really coming from consumers versus retailers.
The podcast conversation made the day-to-day version of this tension even clearer. Packaging technologists described reconciling consumer research findings with EPR and PPWR recyclability requirements and the cost of redesigning a format, often against a tight product launch timeline. One recurring headache was reducing plastic weight in packaging that still has to perform, in cases where a full life cycle assessment can genuinely favour keeping plastic rather than replacing it outright. The workable answer wasn’t abandoning the material. It was making it lighter, more reusable and richer in recycled content, inside a format that’s genuinely recyclable at scale rather than recyclable on paper only. Changes to the Recyclability Assessment Methodology itself, arriving with limited notice ahead of further requirements in 2027, only added to the sense that design teams are working with less runway than the scale of the task deserves.
All of this lands in a market where public trust hasn’t caught up. WRAP’s Spring 2025 Recycling Tracker found that fewer than one in ten UK citizens, just 9%, feel “very confident” about what can and cannot be recycled, which means every investment in circularity is happening ahead of, not alongside, public belief that the system actually works. The lesson worth taking from every one of these conversations is the same one we keep coming back to: regulation and consumer demand can’t be treated as sequential inputs anymore, one after the other. A linear brief, where design gets locked and regulatory review happens afterwards, doesn’t hold up under this much pressure. The businesses ahead of the curve are building a single brief where cost, compliance and consumer input sit together from day one, which only works if a packaging engineer can see the recyclability rating, the fee impact and the material cost of a decision at the moment they’re making it, not weeks later in a compliance review. One dataset informing both the design brief and the compliance case, instead of two teams working from two different pictures of the same product, is the model the next few years of packaging innovation has to be built around.
3. Collaboration is how the packaging industry actually solves this
If there was one word that came up as a close second to regulation this week, it was collaboration. It showed up in the value chain itself: brands are increasingly thinking about the workload they place on suppliers when they ask for data, rather than sending the same lengthy request to every supplier regardless of what’s genuinely needed, and suppliers are asking to be brought into the conversation earlier rather than handed a finished spec after the fact. It showed up in the education happening across associations, councils and PackUK, all running sessions specifically to help the industry keep pace with how fast the rules are changing. And it showed up inside individual organisations too. This year’s show had noticeably more regulatory, ESG and sustainability professionals in the room than in years past, when the audience skewed much more heavily toward packaging and procurement alone, a sign that compliance has genuinely stopped being one team’s job.
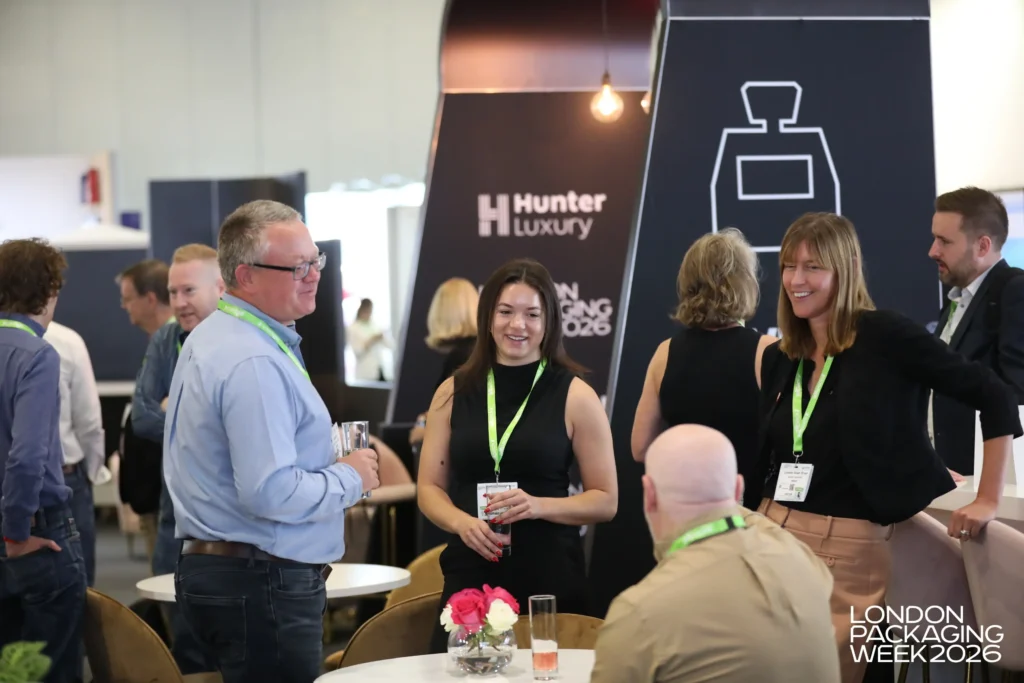
Specright is part of that shift too. We’re genuinely pleased to share that we’ve joined WRAP’s Industry Expert Group for Data Harmonisation, one of four IEG working groups WRAP has set up to align the value chain across the issues reshaping packaging right now. The tone is the same across all four groups: collaboration is how the industry actually gets brands, suppliers, retailers and everyone in between aligned, rather than each business working the problem alone. Our group is focused specifically on data harmonisation, and we’re still in the early stages of mapping out how packaging data can be harmonised across regulatory requirements and the business insight teams need day to day. We first sat down with the group in person a few weeks before the show, and reconnected with many of the same faces over breakfast at London Packaging Week, alongside leading retailers, brands and supporting organisations who are all working this problem from a different seat at the table. Our thanks to WRAP for convening it.
This is, frankly, the same problem a lot of businesses in this industry are quietly trying to solve on their own right now, one company at a time. A shared data language across brands, suppliers and retailers is what makes RAM assessments, EPR reporting, PPWR declarations and DRS separability solvable at scale, rather than something every business has to reinvent from scratch, meaning less duplicated effort across the industry and a better shot at getting ahead of whatever comes next. We’re looking forward to being an active voice in that work over the coming months, and we’ll share what comes out of it as it takes shape. If your own organisation is already thinking about this, it’s worth finding out who in your local associations or working groups is already on it. Chances are, someone is.
Where this leaves packaging teams
The picture that came through all week was consistent with what we’ve been tracking since PPWR’s August deadline: the rules keep multiplying, the fees are compounding, and the teams responsible for compliance are stretched thin. What’s changing is how far the conversation now travels, into board packs, into the design decisions packaging teams make for consumers, and into the industry-wide working groups now trying to get the value chain aligned on a shared set of answers. RAM ratings, EPR reporting and PPWR declarations all trace back to the same root question: whether a company’s underlying packaging data is structured well enough to answer it the first time it’s asked, by a regulator, a retailer, a board or an industry partner.
If your team is still working through what a strong data foundation actually requires, or if you’re trying to work out where your own packaging data stands against pEPR or PPWR requirements, get in touch with our team and we can walk through what that looks like for your portfolio.
-

Danielle Goad
Danielle Goad is the Director, EMEA at Specright, responsible for scaling the company’s presence across EMEA and working with global brands on specification-driven sustainability and compliance. Danielle has held roles across departments at Specright including Customer Success, Product, and Strategic Partnerships over her 7 years with the company. Prior to Specright, Danielle graduated from California Polytechnic State University – San Luis Obispo with her undergraduate in Industrial Technology and Packaging – focused on supply chain.
Explore More Blogs
-

The Only Constant Is Change: What London Packaging Week Confirmed About UK pEPR, PPWR, and Packaging Data
Read More → : The Only Constant Is Change: What London Packaging Week Confirmed About UK pEPR, PPWR, and Packaging Data -

PPWR Compliance and The Data Silo Tax: What Fragmented Packaging Data Is Really Costing You
Read More → : PPWR Compliance and The Data Silo Tax: What Fragmented Packaging Data Is Really Costing You -

Beyond Compliance: Turning Packaging Data into a Business Advantage with Jessie Schwartz
Read More → : Beyond Compliance: Turning Packaging Data into a Business Advantage with Jessie Schwartz
Get Started
With Specright’s Solution Suite, you can digitize, centralize, and link your specification data to drive efficiencies, intelligence, traceability, and collaboration within your organization and across your supply chain network.